Buying a boat in the United States and bringing it back to Canada is a common personal cross-border transaction. The process is manageable when you know what you will pay, which documents you need, and what happens when you reach the Canadian border.
For many U.S.-manufactured boats, the federal duty rate can be 0% under the Canada-United States-Mexico Agreement (CUSMA) when the boat meets the applicable rules of origin. That does not mean the import is tax-free. The 5% Goods and Services Tax (GST), provincial sales tax, trailer costs, registration, and other expenses can still add significantly to the purchase price.
The boat itself is also only part of the transaction. If you are buying a boat and trailer together, the trailer may have its own Canadian registration requirements. The motor and certain removable equipment can also be classified separately for customs purposes.
This guide walks through the process from the point where you are considering the purchase through customs clearance and post-import registration.
Before You Buy: The Costs You Should Expect
Before you agree on a purchase price, it is worth calculating the full Canadian landed cost. A boat that looks like a bargain in the United States can become considerably more expensive once taxes, trailer registration, transportation, and other costs are included.
Federal duty (0% for U.S., Canadian, and Mexican-origin boats under CUSMA)
Boats manufactured in the United States, Canada, or Mexico can qualify for 0% federal duty under CUSMA, provided the applicable rules of origin are satisfied and the origin is properly substantiated at the border.
The important detail is that manufacturing origin matters, not simply where you purchased the boat. Buying a European-built boat from a dealer in Florida does not make it a U.S.-origin boat.
For example, if a Canadian buyer purchases a boat from a U.S. dealer but the vessel was manufactured in Italy, the boat does not automatically qualify for the CUSMA preferential rate.
5% GST on all imports
The 5% Goods and Services Tax applies to every imported boat regardless of origin. It is one of the main costs to include when calculating your total import expense.
The tax is calculated as part of the import accounting process, so your cost estimate should not stop at the purchase price or customs duty.
Provincial sales tax by province of entry
Provincial sales tax can add another significant amount to the transaction. The applicable treatment depends on the province through which you enter Canada and the relevant provincial tax rules. The brief identifies separate PST systems in British Columbia, Saskatchewan, Manitoba, and Quebec, while New Brunswick, Newfoundland and Labrador, Nova Scotia, Ontario, and Prince Edward Island use HST. Alberta, the Northwest Territories, Nunavut, and Yukon do not have a separate provincial sales tax.
This is particularly relevant for snowbirds and buyers who may enter Canada through one province while ultimately registering or keeping the boat in another.
RIV fee for trailers under 15 years old
If your boat comes with a trailer that is less than 15 years old, the trailer may fall under the Registrar of Imported Vehicles (RIV) process. The brief identifies the 2026 RIV fee as approximately $325 plus tax, rather than the older $295 figure that appears in some online guides.
The trailer also has its own compliance and inspection requirements, so buyers should treat it as a separate part of the import transaction.
Provincial trailer plating and insurance
After the trailer clears the federal import process, you may need to complete provincial registration and obtain the appropriate licence plate and insurance.
The exact requirements depend on the province where the trailer will be registered. This means that your import budget should include not only the RIV fee but also provincial registration, plating, and insurance costs.
Optional marine survey
A marine survey is not a customs requirement, but it can be a sensible expense when buying a used boat, particularly when the vessel is expensive or being purchased from a private seller.
A survey can identify structural, mechanical, or safety issues before you commit to the purchase. It is generally much easier to address a problem before the boat has been transported across the border than after it arrives in Canada.
Total effective cost as a percentage of purchase price
There is no single percentage that applies to every boat import. Your final cost depends on the purchase price, origin, province of entry, trailer status, taxes, transportation, and any additional services or inspections.
For a CUSMA-eligible U.S.-origin boat, the absence of federal duty can keep the import cost lower, but GST and provincial taxes still apply. A trailer under 15 years old adds another layer through the RIV process. Higher-value boats may also be subject to the Select Luxury Items Tax, which applies to vessels valued above $250,000 CAD.
The safest approach is to calculate these costs before signing the purchase agreement, not after the boat is already on its way to Canada.
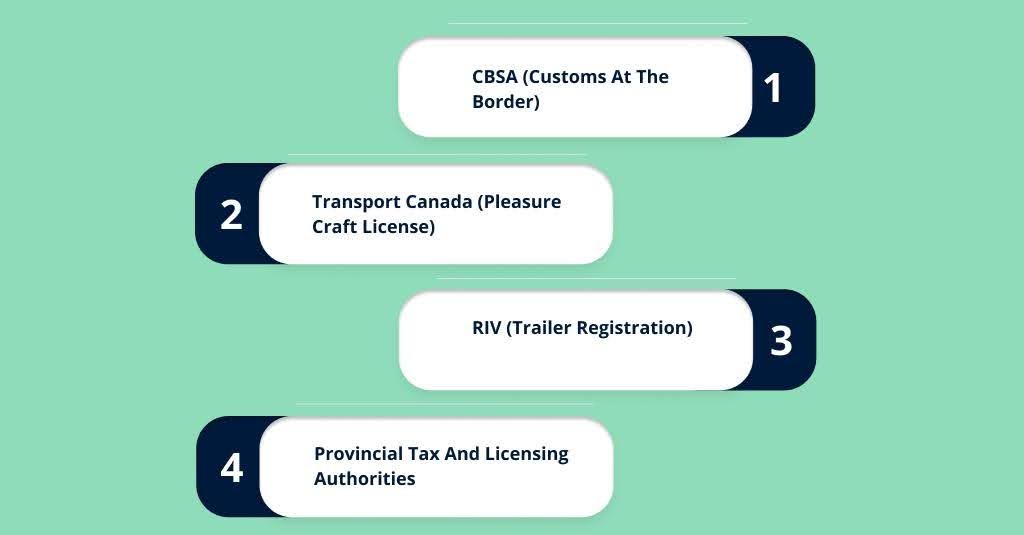
Importing a boat involves several Canadian authorities. Each has a different responsibility, and knowing which agency handles which part of the process makes the transaction easier to understand.
CBSA (customs at the border)
The Canada Border Services Agency (CBSA) handles the customs side of the import. This includes declaring the boat, reviewing documentation, determining the applicable duty and taxes, and collecting the amounts owed at the border.
CBSA also determines the customs classification and reviews the information provided by the importer. Boats generally fall under HS Chapter 89, with pleasure craft commonly classified under HS 8903.
Transport Canada (Pleasure Craft License)
Transport Canada is responsible for the Pleasure Craft Licence framework. If your imported boat has a motor of 10 horsepower or more, you generally need a Pleasure Craft Licence, and the brief specifies a 30-day licensing window following the ownership change.
This is separate from customs clearance. Paying your import taxes at the border does not complete the licensing process.
RIV (trailer registration)
The Registrar of Imported Vehicles (RIV) handles the federal compliance process for applicable imported trailers.
For trailers under 15 years old, the RIV process includes registration and a federal inspection. The brief specifies a 45-day inspection window and identifies the 2026 RIV fee as approximately $325 plus tax.
Provincial tax and licensing authorities
Provincial authorities handle provincial sales tax, vessel registration where applicable, trailer plating, and other provincial requirements.
This is why importing the boat through one province and registering it in another can require additional planning. Your point of entry, intended registration province, and final location of the boat can all affect the costs and administrative steps involved.
With the agencies and major cost categories established, the next question is how Canada determines the federal duty rate for the boat itself, particularly when the vessel was manufactured in the United States, Europe, Japan, or another country.
Federal Duty Treatment for Imported Boats
Once you know the main taxes and fees involved, the next question is usually the most important one: will you have to pay customs duty on the boat itself?
The answer depends primarily on where the boat was manufactured, not simply where you purchased it. A Canadian resident buying a vessel from a U.S. dealer does not automatically receive U.S.-origin treatment. CBSA looks at the boat’s actual country of origin and the documentation supporting that origin claim.
For many Canadian buyers importing from the United States, the good news is that a qualifying U.S.-origin boat can enter at 0% federal duty under CUSMA. Boats manufactured in Canada or Mexico can receive the same preferential treatment when the applicable origin requirements are met.
CUSMA and boats manufactured in the U.S., Canada, or Mexico
The Canada-United States-Mexico Agreement (CUSMA) provides preferential tariff treatment for qualifying goods manufactured in Canada, the United States, or Mexico.
For pleasure craft, this generally means 0% federal duty when the vessel meets the applicable CUSMA rules of origin and the importer can substantiate its origin at the border.
This is an important distinction for used-boat buyers. Suppose you find a 2019 boat at a dealership in Michigan. The fact that the dealer is in Michigan does not establish that the boat is U.S.-origin. If the vessel was manufactured in Europe and later imported into the United States, you need to establish its actual origin before assuming that CUSMA applies.
Before paying a deposit, ask the seller where the boat was manufactured and what documentation is available to support that origin.
CETA and boats manufactured in the EU
Boats manufactured in the European Union may qualify for preferential treatment under the Canada-EU Comprehensive Economic and Trade Agreement (CETA), subject to the applicable origin requirements and documentation. The brief identifies EU-origin boats as potentially entering Canada at 0% duty under CETA.
This is particularly relevant if you are considering a European-built yacht or sailboat purchased from a U.S. seller. Again, the seller’s location does not determine the origin.
A European boat sitting in a Florida marina is still potentially an EU-origin vessel for customs purposes. Before purchase, establish both the manufacturing country and whether you have the documentation necessary to support the preferential treatment.
CPTPP and boats manufactured in Japan or other Pacific Rim countries
The Comprehensive and Progressive Agreement for Trans-Pacific Partnership (CPTPP) can provide preferential tariff treatment for qualifying goods originating in participating countries, including Japan. The brief specifically identifies Japan and other Pacific Rim origins as relevant to the boat-import duty analysis.
If you are importing a Japanese-manufactured boat, do not automatically apply the standard MFN rate. First determine whether the vessel qualifies for CPTPP treatment and whether the required origin documentation is available.
The same principle applies to other CPTPP-origin boats. Preferential treatment depends on the applicable rules, so the country of manufacture should be established before the transaction is finalized.
MFN duty for boats from other origins
Boats that do not qualify for preferential treatment under CUSMA, CETA, or CPTPP can be subject to Most-Favoured-Nation (MFN) duty. The brief identifies approximately 9.5% as the typical MFN rate for non-CUSMA pleasure craft under HS Chapter 89.
That difference can have a substantial effect on the landed cost.
For example, a boat with a customs value of $100,000 CAD could face approximately $9,500 in federal duty before GST and provincial taxes if the applicable MFN rate is 9.5%. A qualifying CUSMA-origin boat, by comparison, may have no federal duty.
This is why checking origin before purchasing can save you much more than trying to resolve the issue after the boat has arrived at the border.
How CBSA determines origin
CBSA does not determine origin simply from the country where you bought the boat. The manufacturer’s country and applicable rules of origin are central to the analysis. The brief specifically lists the boat’s country of manufacture, manufacturing date, legal title, and purchase value among the key attributes to establish before importation.
Keep the seller’s documentation showing the boat’s identity and origin with your other import records. If preferential treatment is being claimed, make sure the documentation supports that claim.
HS Chapter 89 classification and what it means
Pleasure craft are generally classified within HS Chapter 89, which covers ships, boats, and floating structures. The primary heading identified in the brief for pleasure or sport vessels is HS 8903, with further sub-classifications depending on the type and characteristics of the vessel.
For example, the brief identifies HS 8903.10 for inflatable vessels and additional HS 8903 sub-classifications covering different types and sizes of pleasure craft. Fishing vessels fall under HS 8902, while other types of commercial vessels can fall elsewhere within Chapter 89.
The classification matters because the tariff treatment is tied to the classification. It also matters because the boat is not necessarily the only item being imported.
A boat with a trailer and separate marine engine can involve multiple classifications. The brief identifies HS 8407 for spark-ignition marine engines, HS 8408 for compression-ignition marine engines, and HS 8716.10 for trailers.
That is one reason we recommend getting the complete purchase details before the border crossing. A single invoice saying “boat package” may not provide enough information to properly account for every component.
Provincial Sales Tax: What You Owe Depends on Where You Cross
Federal duty is only one part of the tax calculation. Once you know whether the boat is duty-free or subject to MFN duty, you need to determine the provincial sales tax or HST applicable to the import.
The province where you enter Canada can therefore have a meaningful effect on the immediate tax calculation.
Provinces charging PST separately (BC, SK, MB, QC)
British Columbia, Saskatchewan, Manitoba, and Quebec have provincial sales tax systems separate from the federal GST. The brief identifies these as the provinces where PST, RST, or QST may apply alongside the 5% GST.
The exact provincial rate and rules depend on the province, so buyers should check the requirements applicable to their transaction rather than assuming that the GST is the only tax payable.
Provinces charging HST (NB, NL, NS, ON, PE)
New Brunswick, Newfoundland and Labrador, Nova Scotia, Ontario, and Prince Edward Island use the Harmonized Sales Tax system.
For a buyer entering through one of these provinces, the applicable HST forms part of the overall tax calculation.
Territories with no provincial tax (AB, NT, NU, YT)
The brief identifies Alberta, the Northwest Territories, Nunavut, and Yukon as jurisdictions without a separate provincial sales tax. The 5% federal GST still applies.
That does not necessarily mean a buyer can simply choose the lowest-tax province as an entry point and avoid tax obligations elsewhere. Your intended destination, registration, and circumstances matter.
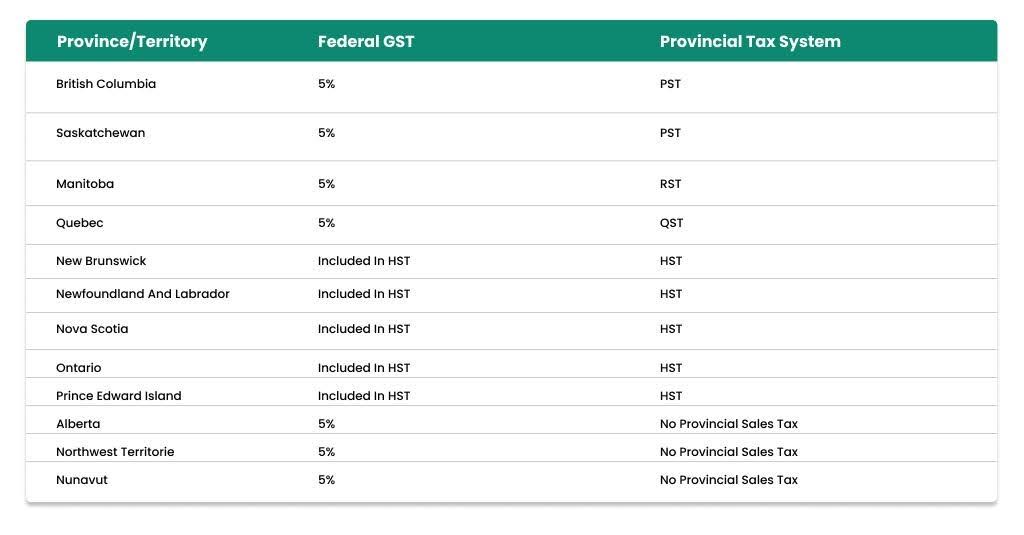
For planning purposes, the important number is your total effective tax rate, not simply the federal GST rate.
| Province/Territory | Federal GST | Provincial tax system |
|---|---|---|
| British Columbia | 5% | PST |
| Saskatchewan | 5% | PST |
| Manitoba | 5% | RST |
| Quebec | 5% | QST |
| New Brunswick | Included in HST | HST |
| Newfoundland and Labrador | Included in HST | HST |
| Nova Scotia | Included in HST | HST |
| Ontario | Included in HST | HST |
| Prince Edward Island | Included in HST | HST |
| Alberta | 5% | No provincial sales tax |
| Northwest Territories | 5% | No territorial sales tax |
| Nunavut | 5% | No territorial sales tax |
| Yukon | 5% | No territorial sales tax |
The actual amount payable should be calculated using the rules applicable to the specific import rather than using the table as a standalone tax determination.
What happens if you enter one province but register in another
This is especially important for snowbirds and buyers who travel through multiple provinces. The province where you cross the border and the province where you ultimately keep or register the boat can be different.
The brief specifically calls for consideration of the point of entry, province of registration, and snowbird registration timing when calculating the effective tax position.
So, if you are planning to bring a boat into Canada through one province but keep it at a marina in another, do not assume that the border crossing alone settles your provincial tax and registration obligations.
The key takeaway is simple: determine the boat’s origin, classification, and intended destination before you calculate the final purchase cost. That information sets the foundation for understanding your duty and tax exposure.
Next, we move to a cost that primarily affects buyers of higher-value vessels: Canada’s Select Luxury Items Tax on boats valued above $250,000 CAD.
The Luxury Tax on Higher-Value Boats
For most buyers, customs duty and sales tax will make up the largest portion of the government’s charges when importing a boat into Canada. However, there is another tax to consider if you are purchasing a higher-value vessel: Canada’s Select Luxury Items Tax.
The luxury tax is separate from customs duty and GST. It is particularly relevant to buyers importing yachts and other vessels with a value above the applicable threshold. Understanding the threshold and calculation method before purchasing the boat can prevent an unexpected tax bill at the border.
Threshold of $250,000 CAD
The Select Luxury Items Tax applies to certain vessels with a value exceeding $250,000 CAD. The brief specifically identifies the $250,000 threshold as an important consideration for higher-value boat imports.
This means a boat valued at $250,000 CAD or less does not become subject to the luxury tax merely because it is an expensive recreational vessel. The threshold is based on the applicable value of the subject vessel.
For buyers considering a large yacht or other premium boat, this should be included in the purchase-cost calculation before committing to the transaction. A vessel that appears to be just below the threshold should also be evaluated carefully because additional transaction costs or valuation issues can affect the final calculation.
The luxury tax is an additional layer on top of the ordinary import taxes and should therefore not be confused with the 5% GST or any applicable provincial sales tax.
How the Tax Is Calculated
The brief specifies two calculation methods for the luxury tax: 10% of the total value or 20% of the amount above the $250,000 threshold, whichever is lower.
For example, if an imported vessel has an applicable value of $300,000 CAD:
- 10% of the total value = $30,000
- 20% of the amount above $250,000 = $10,000
The lower amount would therefore be $10,000.
This calculation is important because simply applying 10% to the entire purchase price can significantly overstate the luxury tax payable.
For a $400,000 vessel:
- 10% of the total value = $40,000
- 20% of the amount above $250,000 = $30,000
The lower amount would be $30,000.
The tax therefore needs to be calculated using the applicable formula rather than treating the threshold as a simple 10% surcharge.
The Canada Revenue Agency (CRA) administers the luxury tax framework, so buyers should retain documentation supporting the value used for the calculation.
Personal Versus Commercial Application
The luxury tax analysis can differ depending on whether the vessel is being imported for personal or commercial purposes. The brief specifically identifies personal versus commercial application as an attribute that needs to be considered when evaluating the tax.
A private individual purchasing a yacht for personal recreational use should therefore assess the luxury tax separately from a business importing a vessel as part of a commercial operation.
The important point for buyers is not to assume that the tax treatment of another boat or another type of transaction will automatically apply to their own purchase. The purpose of the vessel, the nature of the importer, and the circumstances of the transaction can all affect the analysis.
If the boat is being purchased through a corporation, for charter operations, or for another commercial purpose, professional advice may be appropriate before completing the transaction.
When the Luxury Tax Applies to Imported Versus Domestic Vessels
The luxury tax is not limited to boats that are purchased outside Canada. The brief specifically calls for explaining how the tax applies to imported versus domestic vessels.
For an importer, this means the luxury tax should be considered independently from customs duty. A vessel can qualify for 0% CUSMA duty because it was manufactured in the United States, Canada, or Mexico and still potentially attract the luxury tax because of its value.
This distinction is important when estimating the cost of importing a high-value boat. A buyer may correctly establish that no federal customs duty applies but still have GST, provincial taxes, and potentially luxury tax to account for.
For this reason, the statement that a boat is “duty-free” should never be interpreted as meaning that the boat can enter Canada without taxes.
Documents You Need Before You Cross the Border
Once you understand the potential costs, the next step is getting the paperwork ready. Documentation is one of the biggest factors affecting how smoothly a boat crosses the Canadian border.
The brief identifies several documents and pieces of information that should be prepared before the border crossing, including the title, bill of sale, identification, U.S. export filing, cash declarations, and serial-number verification.
Certificate of Title from the U.S. Seller
If you are purchasing a used boat in the United States, obtain the Certificate of Title or equivalent ownership document from the seller.
The title should clearly identify the vessel and establish the seller’s ownership. Where the boat and trailer are separately titled, obtain the relevant documentation for each.
The title is particularly important where the boat has previously been financed or has changed ownership several times. Before purchasing, make sure the seller can provide valid ownership documentation and that there are no unresolved ownership issues.
You should also verify that the information on the title corresponds with the physical boat, particularly the hull identification number.
Notarized Bill of Sale
A detailed bill of sale should identify the boat, motor, and trailer separately where they are being purchased as part of the same transaction.
The brief specifically recommends separate bills of sale for the boat, motor, and trailer.
This is useful because these components can have different customs classifications and potentially different tariff treatment.
The bill of sale should include enough information to establish:
- Buyer and seller
- Purchase date
- Purchase price
- Boat description
- Hull identification number
- Motor information
- Trailer information
- Any other relevant identifying details
Where appropriate, having the document notarized can provide additional evidence of the transaction and its authenticity.
Photo Identification
Bring valid photo identification for the person completing the import transaction.
Your identification should correspond with the purchaser named in the ownership and sales documentation. Having the relevant documents organized together can make it easier for the CBSA officer to verify the transaction.
72-Hour Electronic Export Information Filing on the U.S. Side
If the boat is being exported from the United States, the U.S. export process needs to be addressed before you arrive at the Canadian border.
The brief specifically identifies the 72-hour Electronic Export Information (EEI) filing as part of the documentation process on the U.S. side.
This is an important step that buyers sometimes overlook when concentrating only on Canadian customs.
Do not wait until you are physically at the Canadian border to discover that an export filing or other U.S.-side requirement has not been completed. Build the required export procedures into your transportation schedule.
Cash Declaration if You Paid or Carried Significant Cash
If significant cash is being carried as part of the transaction, make sure you understand the applicable declaration requirements.
The brief specifically includes cash declaration among the pre-border documentation considerations.
This is another reason to maintain a clear paper trail for the purchase. A bank transfer, wire confirmation, or other payment record can help establish how the purchase was funded and support the value declared for customs purposes.
Serial Number Verification
Before leaving the United States, verify the identifying numbers on the actual boat and its components.
The hull identification number, motor serial number, and trailer VIN should correspond with the information shown on your title, bill of sale, and other documentation. The brief specifically identifies serial-number verification as an important pre-border step.
This check is especially valuable for used boats because documentation and physical components may have changed hands over the vessel’s lifetime.
If a number is damaged, unreadable, or does not match the paperwork, resolve the discrepancy before travelling to the border whenever possible.
Handling the Trailer: RIV and Registration
If your boat is being transported on a trailer, remember that the trailer is not simply an accessory that disappears into the boat import process. It is a separate vehicle for regulatory and customs purposes and has its own requirements.
The brief identifies the trailer’s age, VIN, compliance sticker, RIV registration, inspection, provincial plating, and insurance as separate considerations.
The 15-Year Rule for RIV
The trailer’s age determines whether it falls under the Registrar of Imported Vehicles (RIV) process.
Trailers under 15 years old generally require RIV registration, while trailers over 15 years old are exempt from the RIV process but still need to be declared when imported.
This distinction is important when buying a used boat package. A buyer might assume that an older trailer is automatically irrelevant to customs, but an RIV exemption does not mean the trailer can simply be omitted from the import declaration.
RIV Fee and How It Applies in 2026
For trailers subject to the RIV program, the brief identifies the 2026 RIV fee as approximately $325 plus tax.
Older online articles may still quote the previous $295 fee, so buyers should use the current 2026 figure when estimating their import costs.
The RIV fee is only one part of the trailer’s overall cost. You should also account for inspection, provincial registration, plating, and Canadian insurance.
VIN and Compliance Sticker Requirements
The trailer should have a valid, legible 17-digit VIN where applicable, along with the required compliance information.
The brief specifically identifies both the VIN and compliance sticker as attributes that should be checked before importing the trailer.
Before purchasing, inspect the trailer physically. If the VIN cannot be read or the identifying information does not match the paperwork, resolve the problem with the seller before attempting to cross the border.
Federal Inspection at Canadian Tire
Trailers entering the RIV program must undergo a federal inspection at an authorized inspection centre. The brief identifies Canadian Tire as the typical inspection location.
The inspection is intended to verify that the trailer meets applicable Canadian requirements.
45-Day Inspection Window
The inspection must be completed within the applicable 45-day window following importation.
This deadline is important because completing customs clearance does not mean the trailer portion of the import process is finished.
Plan the inspection as part of your post-border schedule rather than waiting until the deadline approaches.
Provincial Trailer Plating
After the federal RIV requirements are satisfied, the trailer must be handled through the appropriate provincial registration and plating process.
Requirements vary by province, so the importer should determine what documents the provincial licensing authority will require before arriving at the registration office.
Canadian Insurance Requirement
The trailer also needs appropriate Canadian insurance coverage once it is being registered and used in Canada.
If the boat and trailer were insured in the United States, contact your insurer or Canadian insurance provider before the trip to understand when the U.S. coverage ends and when Canadian coverage needs to begin.
With the boat, trailer, ownership documents, and tax information prepared, the next major step is dealing with the motor and removable equipment. These items can have separate classifications, making the contents of the purchase package important for customs accounting.
The Boat Motor and Removable Equipment
The boat is not always the only item being imported. If your purchase includes an outboard motor, trailer, GPS, stereo, depth sounder, outriggers, or other equipment, make sure these items are clearly identified in the paperwork. The brief specifically recommends separating the boat, motor, and trailer on the bill of sale because they can be classified differently for customs purposes.
Why separate bills of sale matter
A separate bill of sale for the boat, motor, and trailer gives CBSA a clearer record of what you purchased and how much you paid for each component.
This is especially useful when the boat is purchased as a package from a private seller. Instead of one document stating “boat package: $80,000,” having the hull, motor, and trailer values identified separately gives the importer and customs broker better information for classification and valuation.
HS classification for marine engines
Marine engines are not necessarily classified with the boat itself. The brief identifies HS 8407 for spark-ignition marine engines and HS 8408 for compression-ignition marine engines.
The correct classification depends on the engine’s characteristics, so provide the make, model, fuel type, and other relevant specifications when preparing the import documentation.
Marine safety equipment as duty-free
Certain marine safety equipment can receive duty-free treatment. This is one reason it is useful to identify equipment separately rather than simply assigning its entire value to the boat.
Keep invoices and product descriptions for equipment included with the purchase, particularly when the equipment has significant value.
Accessories: GPS, depth sounders, outriggers, stereos
Accessories such as GPS systems, depth sounders, outriggers, and stereos should also be identified in the purchase documentation.
For a straightforward personal import, the practical approach is to provide CBSA with a complete and honest description of what is included in the transaction. Your customs broker can then determine whether separate classifications are required.
The Border Crossing Itself
After the purchase, U.S. export requirements, transportation, and documentation have been completed, the border crossing is where the import becomes official.
What to expect at CBSA
At a land border, you must declare the boat to CBSA when entering Canada. If you purchased a trailer with the boat, the trailer must also be declared. CBSA advises importers to have the bill of sale and proof of ownership ready.
If the vessel enters Canada by water, the process is different. You must report to a designated marine site and contact the CBSA Telephone Reporting Centre immediately upon arrival.
Declaring the boat and value
The purchase price and supporting documents are used to establish the customs value. Do not understate the price simply because the boat was purchased from a private seller or because you believe the vessel is worth less than you paid.
The sale documents, payment records, title, and other supporting information should tell a consistent story.
The documentation review
The officer may review your title, bill of sale, identification, export documentation, vessel identification numbers, and information about the trailer and motor.
CBSA specifically recommends that buyers of foreign boats obtain the required documents and information from the seller before purchasing.
Tax and fee calculation
Once CBSA has the necessary information, the applicable duty, GST, provincial taxes, luxury tax, and other charges can be determined.
Remember that 0% CUSMA duty does not mean zero tax. GST and applicable provincial taxes still need to be accounted for, and higher-value vessels may also be subject to the Select Luxury Items Tax.
Payment methods and CARM implications
CBSA’s CARM, or CBSA Assessment and Revenue Management, is part of Canada’s modern customs accounting system. The brief specifically calls for explaining its operational relevance for higher-value personal imports.
For a personal importer, your customs broker can explain what accounting or payment arrangements apply to your particular entry.
If something is missing or wrong
Do not assume you can simply drive through and fix documentation later. Missing ownership documents, mismatched identification numbers, incomplete export filings, or unclear values can delay the transaction.
If CBSA cannot establish the required information, the shipment may be held while the issue is resolved. The brief specifically identifies detention and refusal procedures as risks when documentation is incomplete.
After You Cross: Registration and Licensing
Clearing customs is not the end of the process. You still need to complete the Canadian licensing, registration, insurance, and trailer requirements that apply to your boat.
Pleasure Craft License from Transport Canada
Depending on the boat, you may need a Pleasure Craft Licence from Transport Canada. Transport Canada confirms that certain recreational boats require licensing before operation.
The 10 hp motor threshold
The brief identifies 10 horsepower and above as the threshold for the Pleasure Craft Licence requirement.
30-day licensing window
The brief specifies a 30-day window following the ownership change for obtaining the licence.
Keep your CBSA import documentation and proof of ownership because these documents can also be relevant to the licensing process.
Provincial vessel registration
Provincial requirements can vary depending on where the boat will be kept and used. Determine the requirements for your province rather than assuming that federal customs clearance automatically registers the vessel.
Trailer inspection and provincial plating
If your trailer is subject to RIV, complete the federal inspection within the required 45-day period, then proceed with provincial registration and plating. The trailer is treated differently from the boat and has its own vehicle requirements.
Insurance transition
Arrange Canadian insurance before you begin using the boat in Canada. If you brought the vessel from the United States, confirm when your U.S. coverage ends and when Canadian coverage begins.
Special Situations
Buying a boat from a private seller versus dealer
A private purchase is still an import transaction. You need proof of ownership and a clear bill of sale, and the boat’s value must be properly declared.
Boats with an outstanding U.S. loan
Do not purchase a boat with an outstanding U.S. loan without first confirming that the lien can be released and valid ownership transferred. A customs declaration does not eliminate an existing lender’s rights.
Non-residents leaving a boat in Canada temporarily
Non-residents may be able to temporarily import a vessel for personal use. CBSA has a separate framework for foreign vessels temporarily remaining in Canada, including seasonal use.
Boats from Europe (CETA)
EU-origin boats may qualify for preferential treatment under CETA when the applicable origin requirements and documentation are satisfied.
Boats from Asia and other origins
Japanese and other qualifying CPTPP-origin boats may receive preferential treatment. Boats outside the applicable preferential agreements can generally face the MFN rate, which the brief identifies as approximately 9.5% for non-CUSMA pleasure craft.
What Canadian counter-tariffs on U.S. goods do (and do not) affect
The brief specifically requires clarification that Canada’s current counter-tariffs on U.S. goods do not apply to pleasure craft. The measures cover specific steel, aluminum, and automobile categories rather than boats.
Frequently Asked Questions About Importing a Boat into Canada
How much does it cost to import a boat from the USA to Canada?
There is no single import cost. You need to account for the boat’s purchase value, applicable duty, 5% GST, provincial tax, transportation, trailer costs, RIV fees where applicable, and potentially luxury tax.
Is there import duty on used boats from the US to Canada?
A qualifying U.S.-origin boat can receive 0% duty under CUSMA when its origin is properly substantiated. Used status by itself does not determine the duty rate.
Can I buy a boat in the US and bring it to Canada?
Yes. Canadian residents must declare the vessel to CBSA when it is first imported and pay applicable duties and taxes.
What happens to the trailer when importing a boat into Canada?
The trailer is treated separately from the boat. If it is under 15 years old, it generally goes through RIV registration and inspection before provincial plating.
Do I need a customs broker to import a boat into Canada?
You can determine your obligations yourself, but a customs broker can help with classification, documentation, valuation, and customs accounting. Clearit provides Canadian customs brokerage services for importers.
What documents do I need to import a boat from the US to Canada?
The brief identifies the U.S. title, bill of sale, photo identification, U.S. EEI filing, and serial-number information among the key documents.
How is provincial sales tax calculated on an imported boat?
It depends on the province involved. GST applies federally, while some provinces use PST and others use HST. Your point of entry and intended registration location should both be considered.
Are Canadian counter-tariffs affecting U.S. boat imports right now?
According to the brief, pleasure craft are not included in Canada’s current counter-tariff list.
Do I have to pay the luxury tax on a boat under $250,000?
The brief identifies $250,000 CAD as the threshold. Vessels below that value are not subject to the luxury tax merely because they are pleasure craft.
Can I bring a boat from China or Europe to Canada?
Yes, but the duty treatment depends on origin and the applicable trade agreement. EU-origin vessels may qualify under CETA, while other origins may face MFN duty.
What is the RIV fee for a boat trailer in 2026?
The brief specifies approximately $325 plus tax for 2026.
Do I need a Pleasure Craft License after import?
If your vessel falls within the licensing requirements, yes. Transport Canada provides the licensing framework for recreational vessels.
How long does the CBSA border crossing take for a boat?
There is no fixed clearance time. A straightforward entry with complete documentation can be processed at the border, while missing information, valuation questions, or other issues can cause delays.
What if my boat trailer is over 15 years old?
The brief identifies the 15-year threshold for RIV. An older trailer can be exempt from the RIV process, but it still needs to be declared and may have provincial registration requirements.
Can a non-resident bring a boat to Canada for the summer?
Yes. CBSA has a temporary-importation framework allowing non-residents to bring qualifying foreign vessels into Canada for temporary personal use, including seasonal use.
The Bottom Line
Importing a boat into Canada is manageable when you work through the process before the boat reaches the border. Start by confirming its country of manufacture, purchase value, HS classification, trailer age, and included equipment. Then calculate duty, GST, provincial tax, RIV costs, and any applicable luxury tax.
Have the title, bill of sale, identification, export documentation, and identification numbers ready before travelling. At the border, declare the boat and trailer to CBSA, provide the supporting documentation, and pay the applicable amounts.
After clearance, complete the Pleasure Craft Licence, trailer inspection and plating, provincial requirements, and insurance transition.
For a first-time importer, the easiest way to reduce avoidable problems is to have the customs entry reviewed before the boat arrives.